
And for many this may well be the second year in a row because of the poor yields in 2012 coupled with penalties associated with not having met the forward contract targets in 2012.Now prices have come tumbling down in a year when there has been little or no forward selling to avail of the higher prices earlier in the season. The result is that the vast majority of the crop will be offered for sale at harvest and, with many buyers likely to re-sell immediately, this will only add to the price pressure.
First let's look at the effect of price. At €135/t green, a normal 3.2t/ac winter barley crop would generate €430/ac plus straw at around €100 this year. This is a total gross output of €530 for a crop that is costing over €500/ac to grow. Many growers might wish to believe that their costs are much lower but all the different bills must be paid from somewhere.
That would leave you with the area aid at best. And this is before rented land costs are added. With rollover rental costing around €120 to €150/ac and some of the high cost rental running at over €300/ac, it is easy to see where the potential for profit has gone.
Thankfully yields are higher than 3.2t/ac in 2013 but very few growers are likely to average 4.0t/ac. This extra 0.8t/ac (if you have it) will add another €100/ac to output, leaving the potential to pay for the low cost conacre. But it is quite unlikely that poorer conacre will produce these high yields and many owned fields did not produce them either. Actual average yields seem likely to decrease as the harvest progresses.
The simple numbers state that only very high average yields are likely to produce a positive margin on rented ground.
Costs have escalated
There is always plenty of debate about production costs but there is general agreement on the costs produced annually by Teagasc. So whether one uses one's own or Teagasc figures the cost of producing winter wheat is now between €550 and €600/ac. This includes a nominal figure for fixed costs but excludes land rental cost.
Four tonnes of winter wheat at €150/t will pay the bills on owned land, with straw or higher yield adding to the SFP, if there is one. But on €300/ac conacre, juggling the cost numbers is similar to shuffling the deck chairs on the Titanic.
But for many winter wheat growers there is a carryover of debt from last season and it will take exceptional yields to wash these out.
The situation is broadly similar for spring barley. Total production costs range from €450 to €500/ac so 3.0 t/ac at €135 would generate €405/ac. Some average yields will be better but many will be below three. And some of the rented land on which spring barley is grown was also very expensive.
Thankfully, most rented land came at modest cost but with these production costs and prices there is not enough income to pay for land at any price. Good straw prices add to the gross output, provided you have a customer who pays.
maize - the bottom line?
Do prices really need to be as low as currently indicated? We must acknowledge that the market is the market and it works in our favour on the way up so we must live with it coming down.
We are all too aware that the expectation of a huge US maize harvest is the downward driver. Maize is in demand and very attractive at prices of €180/t (and possibly less in the future).
However, many will say that there will be no maize delivered for €180/t until December and that there is likely to be a lot of feed consumed before then. And many diets have a specific need for barley inclusion.
It must also be stated that the quoted maize prices are ex-port and that transport will add €5 to €15/t.
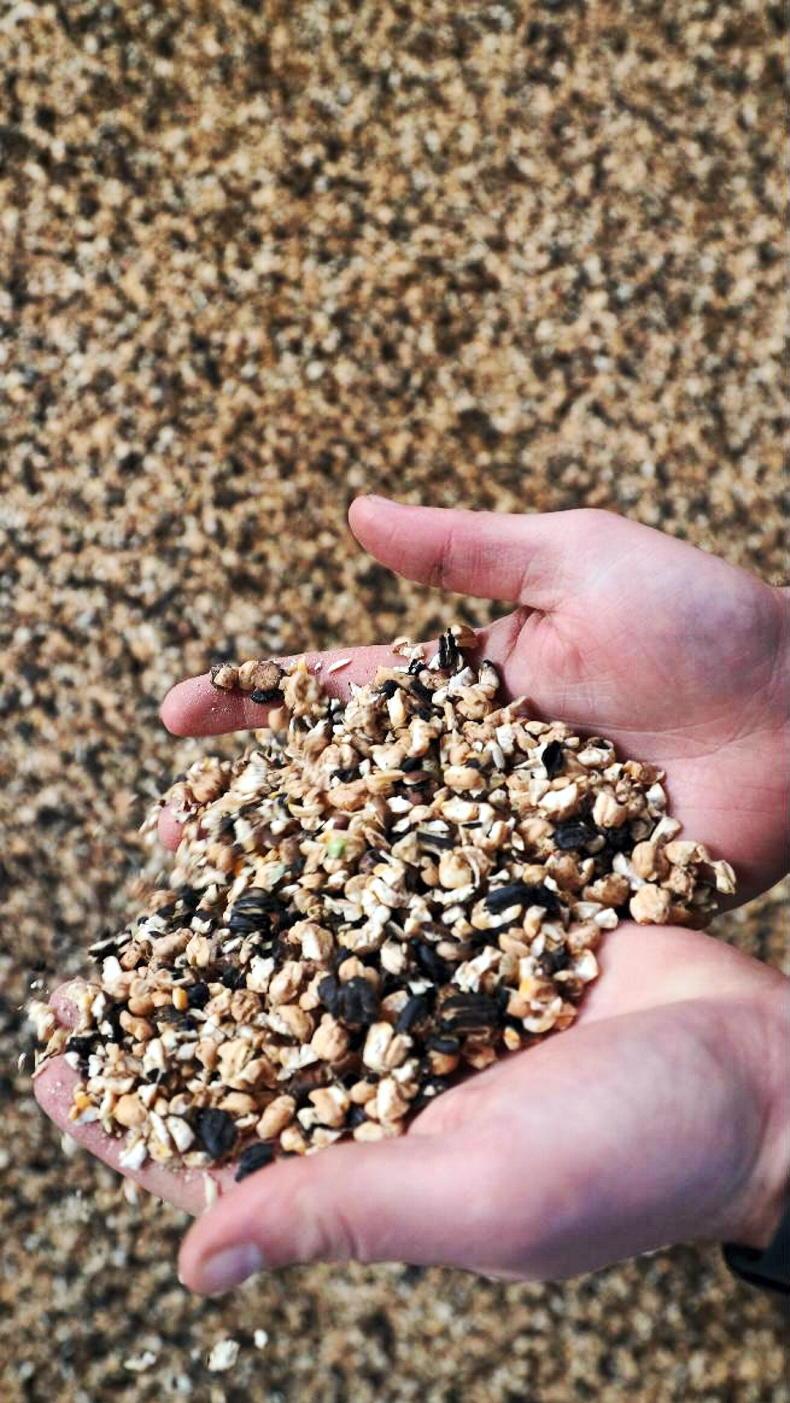
Maize must also be processed before use, adding to its cost relative to rolled barley. Eighteen per cent moisture barley can be rolled and treated at the same time off the combine.
So is the claim of €180 for maize misleading? For the big milling buyer who has to haul grain, regardless of type, and who can only produce compound rations, the answer is possibly no, at least from December onwards.
But for many smaller mills around the country, especially those producing coarse rations, it seems reasonable that native grains can carry a much higher value into rations, at least in the medium term.