

Positivity has hit the factory trade over the last few weeks, with greater demand seen from factories, which appear to be looking to fill orders early on in the season.
The beef kill for last week was up 3,340 (roughly 11%) on the same week last year, though we are still significantly behind the throughput figures seen in 2025. That figure stood at 1,215,819 this time last year but currently sits at 1,184,783, back 31,036 head.
With 13 weeks left in the calendar (with reduced kill numbers during Christmas week and the week after) if figures remain at circa 3,300 head ahead of the corresponding week for last year, 2026 may just about match the 2025 kill throughput.
Last year was an historically low year, so this is the bare minimum you'd hope for.
Increasing quotes
In an effort to coax more cattle out, factories have been increasing quotes, with €7.20 of a flat price being offered for Angus-cross heifers this week. For beef bullocks and heifers, €6.60/kg and €6.70/kg of a base price apply at most factories.
Surprisingly, we haven’t seen the same demand in marts, with a reduction in prices for cattle weighing over 600kg this week. Last week saw heifer prices skyrocket by 22c/kg on average, while this week witnessed a slip in price of 17c/kg.
That still leaves these heifers at 5c/kg higher than two weeks ago but, in reality, it only leaves a 650kg heifer at €32.50 more.
Marts are variable, and some managers are reporting a higher price for finished-type heifers. Bullocks have seen their 6c/kg lift almost eroded by a 5c/kg cut this week as well.
Mart or factory?
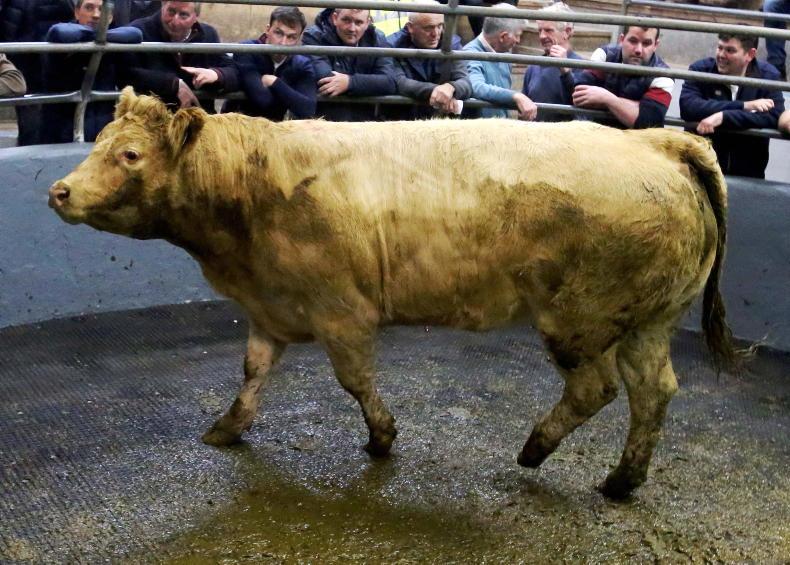
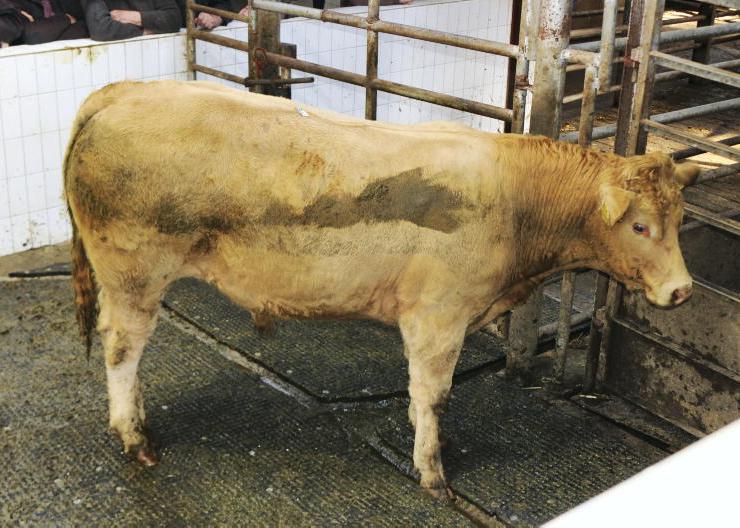
Taking that 650kg heifer at an average price of €3.87/kg, our mart cheque would come to €2,515.50 before any stoppages.
If we take the average price paid of €6.90/kg for heifers (bonuses for confirmation, QA, etcetera) and a carcase kill out of 56%, we sit at a price of €2,511.60 for a 364kg carcase.
There is a lot more at play here than just simple calculations, with kill-out potential, bargaining power and agent presence at rings all to be factored in, but there is a marked shortening of the difference in factory and mart trade.
Weanlings and culls
Weanling bull prices are relatively steady, even with an increase in numbers, with no great price increase or decrease for bull weanlings. Bulls below 300kg are an exception, with prices slipping by 6c/kg.
Farmers' and finisher activity has ramped up over the last number of weeks due to grass growth, while exporters are still present and vying for the top lots on offer.
With several larger exporters moving weanlings in the next week, there should be a sharper interest once sheds are emptied.
In the heifer ring, light weanling heifers are back 28c/kg in a week, though heavier heifers are proving a much firmer trade, with 400-450kg lots up 20c/kg and 450kg+ lots up 16c/kg.
In the cull-cow ring, trade has moved in a more positive direction. Average prices increased by 12c/kg this week to €2.87/kg, with the top and bottom thirds up by 15c/kg and 6c/kg, respectively, to trade at €3.52/kg and €2.11/kg on average.



SHARING OPTIONS